5 FX Risk Management Strategies for International Businesses
Fluctuating exchange rates can significantly impact your bottom line by increasing the cost of goods and services. Learn five practical strategies, including natural hedging and forward contracts, to mitigate these risks and stabilize your business cash flow.
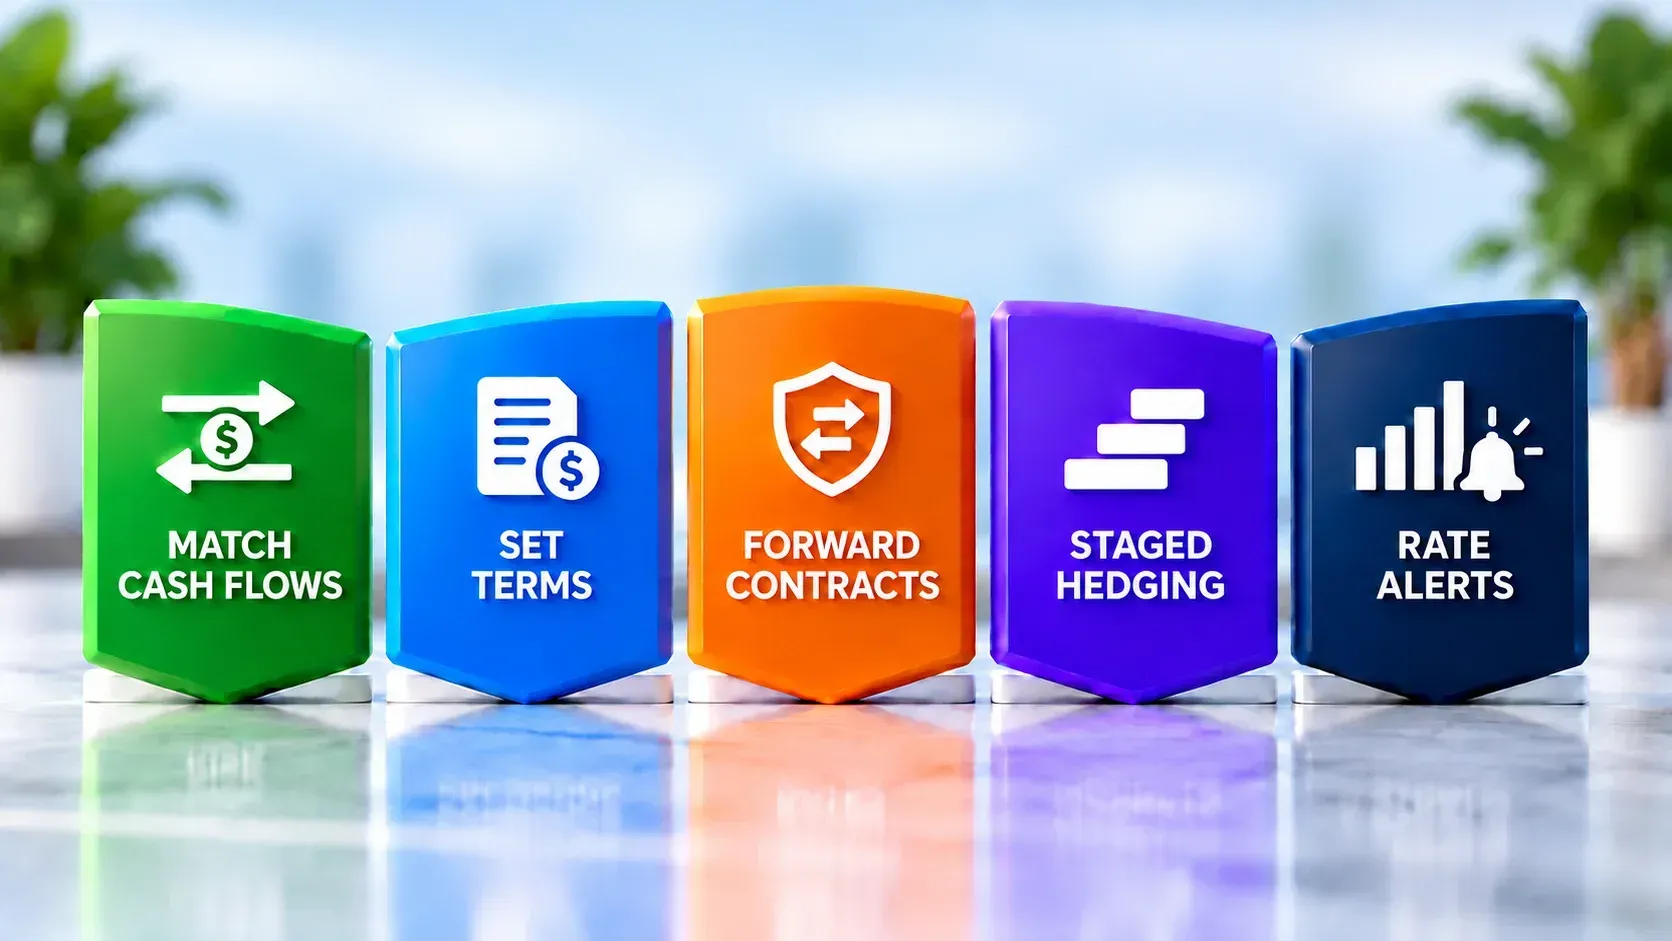
FX risk management strategies help businesses limit the effect of exchange rate changes on future costs, revenue and cash flow. Five approaches worth comparing are matching foreign currency income with expenses, setting clear invoice terms, using forward contracts, hedging in stages, and using market orders and rate alerts to plan conversions. Each offers a different balance of certainty, flexibility and cost.
For a Canadian business paying overseas suppliers or collecting from international customers, the useful question is not where a currency will go next. It is how much a change in the rate would affect the business before a payment is due. This guide compares the five approaches so you can decide which fits your transactions.
How can exchange rate movements affect a Canadian business?
Say a Canadian company has a USD 100,000 supplier invoice due in three months. At an illustrative rate of USD/CAD 1.36, the invoice would cost CAD 136,000. If the rate is 1.40 when payment is due, it would cost CAD 140,000: CAD 4,000 more for the same goods, before any conversion costs. Those extra dollars must come from the company’s margin, its budget or its customer prices.
You can use a currency calculator to estimate a payment at current rates, then check the actual rate and fees that would apply to a transaction.
1. Match foreign currency income with expenses
If your business receives and pays in the same currency, it may be able to use incoming funds to meet outgoing obligations. This is often called a natural hedge. It can reduce the amount that needs converting without relying on an exchange rate prediction.
When does it work?
It works best when the currencies, amounts and dates line up reasonably well. For example, a Canadian software business collecting USD from US clients may also pay USD for hosting or contractors. It can use some of those receipts for those bills instead of converting the full revenue into CAD and later buying USD again.
What would the numbers look like?
Suppose the business expects USD 80,000 in receipts and owes USD 60,000 in expenses in the same month. If the receipts arrive before the bills are due, it can use USD 60,000 directly and consider how to manage the remaining USD 20,000. A live exchange rate can help estimate the CAD value of that remaining exposure, although the rate available for a transaction may differ.
What is the trade-off?
Matching cash flows only helps with the portion that overlaps. A late customer payment could leave the business needing USD before it arrives, and the unmatched USD 20,000 still changes in CAD value. Holding foreign currency also means watching how much CAD the business needs for payroll, taxes and other domestic expenses.
| Field | Value |
|---|---|
Amount Payable (USD) 35,000 | |
Bank Exchange Rate 1.4493 / 0.6900 | |
Total cost 50,726.84CAD |
| Field | Value |
|---|---|
Amount Payable (USD) 35,000 | |
MTFX Exchange Rate 1.4245 / 0.7020 | |
Total cost 49,856.53CAD |
You Save
CAD 870.31
with MTFX
13 October 2026
We use mid-market rates. This is for informational purposes only. Log in to view send rates.
2. Agree on invoice currency and pricing terms
The currency and price written into a customer or supplier agreement determine who carries much of the exchange rate risk. Businesses can consider these terms before a quote is accepted, when there may still be room to negotiate.
Could you invoice in CAD?
A Canadian exporter paid in CAD knows how many Canadian dollars it will receive. The overseas buyer then faces the currency conversion. That may be attractive to the exporter, but buyers can resist a price in an unfamiliar currency or request a concession in return.
Could the contract share the risk?
A longer agreement might specify when prices can be reviewed if exchange rates move beyond an agreed level. For example, a Canadian manufacturer and its US buyer could agree to revisit prices at the next quarterly review if their reference rate changes substantially. The clause needs a clear reference rate, review date and calculation method so both sides know what they have agreed to.
What is the trade-off?
Changing the invoice currency may shift the exposure to the other party rather than remove it from the commercial relationship. Price adjustments also depend on bargaining power and contract terms. Changing the invoice currency may shift the exposure to the buyer rather than remove it. A price adjustment clause can offer another way to share the impact of exchange rate movements, but the terms may be difficult to negotiate.
3. Fix a rate for a known future payment or receipt
A forward contract is one of the most versatile FX risk management services where you set a rate for exchanging a specified amount of currency on a future date or within the agreed contract terms. It is one of the clearest currency hedging strategies when the business knows what it will pay or receive.
When does a forward fit?
It fits a confirmed obligation with a reasonably clear amount and date. A Canadian importer with a signed USD 100,000 invoice due in three months can arrange the exchange in advance and know the CAD cost covered by the contract, subject to its terms. That makes it easier to set a budget or a selling price.
What does the certainty cost?
Suppose the agreed forward rate were an illustrative USD/CAD 1.37. The USD 100,000 covered by the contract would cost CAD 137,000 under that rate, excluding any other contractual costs. If the rate at payment time were 1.40, that certainty would have been valuable to the importer. If it were 1.32, the importer would still be committed to the agreed terms and would miss the more favourable rate.
What should be checked first?
Match the contract amount and timing to the underlying business payment. If a projected purchase is cancelled or delayed, the currency commitment may remain and changing or closing it could have a cost. The aim is to cover a business need, not to make a bet on the exchange rate.
Match the contract amount and timing to the underlying business payment. If a projected purchase is cancelled or delayed, changing or closing the forward could have a cost. That is why mapping your exposure before choosing a hedge matters more than guessing where the exchange rate will go.
4. Hedge exposure in stages
A business does not have to decide on the full amount at one time. Partial or layered hedging means covering portions of an expected exposure at different dates, often as the underlying payments become more certain.
When does a staged approach fit?
It can suit a company with recurring USD supplier bills or forecast sales that may change. Confirmed orders may justify more coverage than an early sales forecast. The business can set a rule for what share to cover as each payment becomes clearer.
How might it work in practice?
Imagine a Canadian retailer expects to need USD 300,000 over the next six months. It could cover USD 100,000 linked to confirmed orders now, then revisit the remaining exposure as orders are placed. This avoids committing to the entire forecast before the retailer knows whether it will actually need all of the currency.
What is the trade-off?
The uncovered portion still moves with the exchange rate. Covering amounts at different times may smooth the effect of any one decision, but it does not guarantee a better average rate. The business also needs a clear rule for when to add coverage, rather than postponing each decision in the hope that rates improve.
5. Use market orders and rate alerts to plan conversions
When a business has some flexibility over when it converts funds, it can set a target rate in advance. A market order can be set to execute a conversion if that rate is reached. A rate alert notifies the team when a chosen level is reached so someone can decide whether to act. Both can support a plan for payment timing, provided the business also has a deadline if the target is missed.
When might a market order fit?
Suppose a Canadian importer will need USD 100,000 in six weeks and has room to convert some of it early. The business could set a target order to buy USD 25,000 if its desired rate becomes available. If the order executes, that portion is converted; the remaining USD 75,000 still needs a plan.
What can a rate alert do?
A rate alert can notify the finance team when a chosen level is reached. The team can then review its cash needs and decide whether to convert. The alert itself neither places an order nor secures the rate shown in the notification; the rate available when the team acts may differ.
What is the trade-off?
The target may never be reached. Until an order executes or the business converts another way, its future payment remains exposed to rate movements. For a firm invoice, set a latest date for buying the required currency and decide what to do if the target rate has not appeared by then. An unfilled order is different from a forward contract, which fixes a rate under its agreed terms.
How do these five approaches compare?
The right fit depends on whether the business can change its commercial cash flows, how certain its payments are and how much exchange rate movement it can absorb.
These approaches can work together. A company might first match its USD receipts against USD expenses, then consider a forward for a confirmed balance. It could convert an amount that has flexible timing when a target rate is reached, while keeping a deadline for the rest.
How certain is the payment you’re planning around?
The more certain a foreign currency payment becomes, the easier it is to decide how much of it needs a known exchange rate. A signed invoice due on a set date gives a business more to work with than a sales forecast that may never turn into a payment.
A confirmed payment has a clearer amount and deadline
Once a business has accepted a supplier invoice, it can compare the currency amount and due date with its available cash and expected receipts. If the CAD cost would put a planned margin under pressure, securing a rate for some or all of that payment may make sense.
A forecast can change before it becomes an invoice
A sales team might expect a large order next quarter, but the customer could buy less, delay the order or decide against it. Committing to exchange a currency amount based on the full forecast could leave the business with more currency than it needs. One approach is to review the forecast regularly and make firmer decisions as orders are confirmed.
The due date may be less certain than the amount
Even a confirmed customer invoice does not guarantee the payment will arrive on the expected day. When timing is uncertain, the business should consider how it would meet an earlier obligation or handle a later receipt. That question matters especially when matching incoming currency to an outgoing payment.
How would two businesses handle the same USD invoice?
Imagine two Canadian importers each have a USD 75,000 supplier invoice due in 90 days. If USD/CAD rises by five cents before payment, each invoice costs CAD 3,750 more. The exchange rate movement is the same, but its effect on each business is different.
Business A has a narrow margin
Business A has already agreed on a CAD selling price and expects a CAD 4,000 margin on the order. An extra CAD 3,750 in supplier costs would leave just CAD 250 of that margin, before any other changes. Knowing the CAD cost of most or all of the invoice may be more useful to this business than waiting for a potentially better rate.
Business B has more room to adjust
Business B has not yet set its customer price and has a wider margin. It may decide to cover part of the invoice now and review the remaining amount when its selling price is final. If it uses a target rate for a portion it can convert early, it still needs a deadline for buying any USD required at payment time.
The useful comparison is how much uncertainty each business can carry while meeting its obligations and protecting its planned margin.
How should a business choose an FX risk management strategy?
Start with the payments and receipts, then decide how much uncertainty the business can carry. A simple process is often more useful than trying to predict the next currency move.
- Map the cash flows. List expected foreign currency receipts and payments by currency, amount and due date. Separate confirmed invoices from forecasts.
- Measure the possible impact. Calculate what a reasonable adverse rate movement would do to CAD costs, revenue and margins. For context, currency charts show past movements, but past rates cannot tell you what will happen next.
- Decide how much needs protection. Match currency inflows and outflows first, then decide what share of the remaining exposure needs a known rate. Check that any commitment fits the cash flow and contract dates.
- Set a review rule. Revisit the plan when payment amounts, dates or business margins change. Daily FX updates can add market context, but they should not replace a plan based on the company’s obligations. Bank currency forecasts can inform scenarios without determining a payment decision.
The review rule should include a final decision date for any payment being monitored with a rate alert or target order. That way, a desired rate does not become a reason to leave an invoice unattended.
What happens when an invoice amount or payment date changes?
An FX plan should follow the underlying business transaction. When an order, invoice or payment schedule changes, the amount and timing of the currency exposure can change with it.
If the amount changes, recalculate what remains
Suppose a business expected a USD 90,000 purchase, but the final supplier invoice is USD 65,000. Its currency requirement is now USD 25,000 smaller. It should compare the revised invoice with any conversions or currency commitments already made, then decide what action is needed under their terms.
If the date changes, check every related deadline
A supplier that moves a payment date from June to August changes when the business needs the currency. That may affect a planned conversion, a target order or the terms of an existing forward contract. Changes to a contract may involve a cost, so the business should check its terms as soon as the new date is known.
Keep one current view of the exposure
The finance team needs an up-to-date record of the currency, amount, expected date and how much has already been covered. Updating that record when the transaction changes helps prevent a decision based on an outdated invoice or forecast.
How can you tell whether your FX approach is working?
A favourable market rate is not the only measure of success. The more useful test is whether the business achieved the cost or revenue certainty it needed when it made the decision.
Compare the result with the original budget
Record the CAD amount the business expected when it priced the transaction, then compare it with the final CAD amount after applicable conversion costs. If a business budgeted CAD 150,000 from an international sale and received CAD 149,000, it can see the CAD 1,000 difference and assess its effect on the planned margin.
Check how much exposure remained
A business may have protected one portion of a payment and left another open to exchange rate changes. Reviewing the result of each portion shows whether the chosen level of coverage gave the business enough certainty. It also helps identify recurring payments that deserve a more consistent approach.
Review the decision, not just the final rate
A rate available after the payment was made can make an earlier decision look better or worse in hindsight. Instead, ask whether the business followed its plan, met its payment deadline and kept the outcome within the range it could afford. Those answers are more useful when deciding what to change for the next transaction.


Make the currency decision before the payment is due
The most useful FX risk management strategies start with a clear view of what the business will pay or collect, when it will happen and how much movement its margins can withstand. From there, a business can choose the right mix of natural matching, contract terms and hedging for each exposure. The goal is a payment or revenue outcome the business can plan around, not a perfect guess about tomorrow’s rate.
Create your business account in minutes and talk to our FX specialist to find the right currency risk management strategy for your business.
FAQs
1. What are FX risk management strategies?
FX risk management strategies are ways to reduce or control how exchange rate movements affect business costs, revenue and cash flow. They include matching foreign currency inflows and outflows, setting contract terms and hedging future transactions.
2. Which strategy fits a confirmed future supplier payment?
A forward contract can fit a confirmed foreign currency payment when the amount and timing are clear and the business wants a known exchange rate. The contract’s amount, date and other terms should match the supplier obligation.
3. Can a business reduce currency exposure without a forward contract?
Yes. A business may match foreign currency income with expenses or negotiate invoice currency and pricing terms. These approaches depend on the timing of cash flows and what customers or suppliers will agree to.
4. How do market orders and rate alerts differ?
A target market order is intended to execute a currency conversion if its specified conditions are met. A rate alert sends a notification when the chosen level is reached, leaving the business to decide whether and when to convert.
5. Should a business hedge all of its foreign currency exposure?
Not necessarily. The appropriate share depends on how certain the payments are, how much risk the business can absorb and whether it already has offsetting cash flows in the same currency. Covering an uncertain forecast in full can create a commitment larger than the eventual need.
6. What if a target exchange rate is never reached before payment is due?
The business still needs to meet its payment obligation. It should set a latest conversion date in advance and decide how it will obtain the currency if an order remains unfilled, rather than relying on the target rate appearing before the deadline.
7. How often should a business review its currency risk strategy?
Review it whenever the amount or timing of significant foreign currency cash flows changes. A scheduled review is also useful for recurring exposure, especially when margins, contract prices or payment forecasts have changed.
Disclaimer: This article is for general information only and does not constitute financial, legal or accounting advice. Exchange rates and business circumstances change, and the examples are illustrative. Review the terms of any currency arrangement and seek independent professional advice before making a decision.
Compare FX rates and manage global business payments.