US Dollar Forecast & Global FX Outlook - September 2026
 Written by Ash Abbasi
The US dollar enters the second half of September with stronger policy and safe-haven support after the Federal Reserve raised interest rates for the first time since 2023. August payrolls rebounded and headline inflation remained elevated, although softer core inflation may limit further tightening. The September outlook continues to see USD/CAD trading mainly between 1.37 and 1.41, EUR/USD between 1.14 and 1.19, GBP/USD between 1.33 and 1.39, and USD/JPY between 156 and 162.
USD Outlook: Fed rate hike reinforces support as labour market rebounds
The Federal Reserve raised its target range to 3.75%–4.00% on September 16 in a unanimous decision, citing resilient domestic demand and continued inflation risks. The move followed a rebound of 162,000 in August payrolls, while unemployment remained at 4.1% and July’s initially reported employment decline was revised to a gain of 21,000.
August headline CPI remained at 3.4% year over year and increased 0.4% during the month, although core inflation eased to 2.4%. This combination should keep the USD supported through higher Treasury yields, but improving underlying inflation and the economic effects of tighter policy may limit further gains.
Attention now shifts to the Fed’s post-meeting guidance, Treasury market movements and the September 30 releases of the third estimate of second-quarter GDP and August PCE inflation.
USD Year-to-Date Performance
| Currency Pair | Sep 01, 2026 | Monthly Change | Yearly Change |
|---|---|---|---|
| USD / CAD | 1.39 | -1.04% | 0.65% |
| EUR / USD | 1.16 | 0.57% | -0.40% |
| GBP / USD | 1.35 | 0.45% | 1.10% |
| USD / JPY | 160.02 | 1.54% | 7.87% |
| USD / CHF | 0.81 | 0.28% | 0.67% |
| USD / CNY | 6.72 | -0.43% | -5.84% |
| USD / INR | 94.89 | -0.52% | 7.84% |
| AUD / USD | 0.71 | 1.74% | 9.59% |
| NZD / USD | 0.59 | 0.37% | 0.55% |
| USD / MXN | 16.99 | -2.01% | -9.19% |
US Dollar Forecast – September 2026
The base case is for a supported but uneven US dollar. The Fed’s September rate increase confirms the dollar’s near-term yield advantage, while resilient payroll growth and elevated headline inflation reduce the case for an early policy reversal. However, softer core inflation, higher borrowing costs and continuing geopolitical uncertainty may prevent a broad, sustained USD rally.
Forecasts pin USD/CAD at 1.39, USD/JPY at 160, USD/CHF at 0.80, EUR/USD at 1.19, and GBP/USD at 1.38 for Q4 2026. These levels point to a broadly stable near-term dollar, followed by gradual weakness into 2027.
What's Driving the US Dollar in September 2026?
US Dollar Forecasts - September 2026
| Currency Pair | Dec 2026 | Mar 2027 | Jun 2027 | Sep 2027 |
|---|---|---|---|---|
| USD / CAD | 1.39 | 1.38 | 1.36 | 1.36 |
| EUR / USD | 1.19 | 1.20 | 1.20 | 1.20 |
| GBP / USD | 1.38 | 1.39 | 1.39 | 1.39 |
| USD / JPY | 160 | 158 | 158 | 158 |
| USD / CHF | 0.80 | 0.78 | 0.77 | 0.77 |
| USD / CNY | 6.60 | 6.60 | 6.50 | 6.50 |
| USD / INR | 95.5 | 96.0 | 96.5 | 97.0 |
| AUD / USD | 0.70 | 0.71 | 0.72 | 0.73 |
| NZD / USD | 0.61 | 0.62 | 0.62 | 0.63 |
USD Outlook September 2026 - FX Highlights & Monthly Ranges
| Currency | Market News | |
|---|---|---|
CAD | USD/CAD ForecastExpected range: 1.37 – 1.41 USD/CAD is expected to trade between 1.37 and 1.41. The Canadian dollar is supported by the Bank of Canada’s mildly hawkish hold, headline inflation of 3.0% and elevated oil prices. However, Canada’s 42,000 employment decline, the Fed’s rate increase and continuing tariff uncertainty favour two-way volatility and limit the scope for sustained CAD appreciation. Canadian counter-tariffs are now in effect, while the Quebec election, Alberta referendum and US midterm campaign may generate additional trade and constitutional headlines. → View the USD/CAD charts | |
EUR | EUR/USD ForecastExpected range: 1.14 – 1.19 EUR/USD is expected to trade between 1.14 and 1.19. The European Central Bank raised its key interest rates by 25 basis points, taking the deposit rate to 2.50%, but the simultaneous Fed increase preserved the dollar’s yield advantage. Persistent European inflation provides some support for the euro, while high energy costs and the economic consequences of the Middle East conflict create downside risks. Relative central-bank guidance and movements in energy prices should determine whether EUR/USD can approach the upper end of its September range. → Track EUR/USD movements | |
GBP | GBP/USD ForecastExpected range: 1.33 – 1.39 GBP/USD is expected to trade between 1.33 and 1.39. Sterling remains supported by a Bank Rate of 3.75%, although the Fed’s September increase has strengthened the dollar side of the pair. The Bank of England’s September 17 decision is the immediate catalyst. A firm inflation message would support GBP, while concern about growth or signals of future easing could push the pair toward the lower end of its projected range. → Monitor GBP/USD trends | |
JPY | USD/JPY ForecastExpected range: 156– 162 USD/JPY is expected to trade between 156 and 162. The Fed’s rate increase has reinforced the wide US–Japan yield gap, keeping upward pressure on the pair despite continuing Japanese intervention concerns. The Bank of Japan’s September 18 decision will be critical. More hawkish guidance could support the yen and pull USD/JPY lower, while unchanged policy accompanied by cautious communication would leave the pair vulnerable to another move toward 162. → Follow USD/JPY movements | |
AUD and NZD | AUD/USD & NZD/USD ForecastExpected ranges: AUD/USD is expected to trade between 0.70 and 0.74, while NZD/USD is projected between 0.58 and 0.62. Both currencies remain sensitive to Chinese demand, commodity prices and global risk appetite. The Fed’s rate increase presents a near-term headwind, but resilient commodity markets may provide partial support. Escalating geopolitical risks or weaker Chinese data would favour the USD, while improving global growth expectations could lift both currencies toward the upper ends of their ranges. → Compare USD rates | |
What Economic Data to Watch This Month
Most of September’s major US catalysts have now passed. August payrolls increased by 162,000, unemployment remained at 4.1%, headline CPI held at 3.4%, and the Federal Reserve raised rates by 25 basis points on September 16.
Attention now turns to the Bank of England and Bank of Japan decisions, together with the market’s interpretation of the Fed’s post-meeting guidance. Treasury yields and oil prices will remain important short-term drivers of dollar performance.
The final major US releases arrive on September 30, when the third estimate of second-quarter GDP and August PCE inflation are published. Canadian retail sales and GDP will also influence USD/CAD before month-end.
| Currency | Date | Event |
|---|---|---|
| CAD | Aug 31, 2026 | August S&P Global Manufacturing PMI |
| USD | Aug 31, 2026 | July JOLTS and August ISM Manufacturing |
| CAD | Sep 1, 2026 | Bank of Canada Rate Decision |
| CAD | Sep 2, 2026 | July Trade Balance |
| USD | Sep 2, 2026 | July Trade Balance and August ISM Services |
| USD | Sep 3, 2026 | August Employment Situation |
| CAD | Sep 3, 2026 | August Labour Force Survey |
| CAD/USD | Sep 7, 2026 | Canadian Countertariffs Take Effect |
| EUR | Sep 9, 2026 | European Central Bank Rate Decision |
| USD | Sep 10, 2026 | August Consumer Price Index |
| CAD | Sep 13, 2026 | August CPI and July Manufacturing Sales |
| CAD | Sep 13, 2026 | Calgary-Shaw Provincial By-Election |
| USD | Sep 15, 2026 | August Retail Sales and Federal Reserve Decision |
| GBP | Sep 16, 2026 | Bank of England Rate Decision |
| JPY | Sep 17, 2026 | Bank of Japan Rate Decision |
| CAD | Sep 23, 2026 | July Retail Sales |
| CAD | Sep 28, 2026 | July GDP |
| USD | Sep 29, 2026 | Q2 GDP Third Estimate and August PCE Inflation |
Frequently asked questions
The US dollar is expected to remain firm but uneven after the Federal Reserve raised rates to 3.75%–4.00%. Resilient employment and sticky headline inflation provide support, although easing core inflation may limit further gains. The expected monthly ranges are 1.37–1.41 for USD/CAD, 1.14–1.19 for EUR/USD, 1.33–1.39 for GBP/USD and 156–162 for USD/JPY. You can also check the daily currency commentary for the most recent updates and convert CAD to USD at the right time.
The dollar could strengthen if August PCE inflation remains elevated, Treasury yields rise or the Fed indicates that further tightening is possible. Persistent geopolitical risk would also support safe-haven demand. A broad, sustained rally is less certain because labour-market momentum has weakened and several major currencies are already expected to recover gradually through 2027. Check out what top Canadian banks are forecasting for the USD.
The dollar could weaken if PCE inflation slows, economic activity deteriorates, or the Fed signals that September’s increase was sufficient. Falling Treasury yields or reduced geopolitical risk would add pressure.
The main drivers are the Fed’s 25-basis-point rate increase, US Treasury yields, resilient payroll growth, persistent headline inflation and safe-haven demand related to the Middle East conflict. Election headlines are a secondary source of volatility through their implications for trade and fiscal policy.
The Fed decision has passed, but the Bank of England and Bank of Japan meetings may still generate volatility. September 30 could also produce larger moves when US GDP and PCE inflation are released. Reviewing historical exchange rates can provide useful context before you send money to the US.
That depends on the currency being sold and the timing of the payment. Staggering transfers or using a forward contract can reduce exposure to short-term movements following the Fed’s rate increase. In an uneven market like September 2026, using tools such as rate alerts or splitting transfers can help reduce risk.
Companies making business payments should focus on August PCE inflation and the third estimate of second-quarter GDP on September 30, alongside Treasury yields, Fed communication, oil prices and incoming employment indicators. These economic releases can affect USD exchange rates and create short-term volatility across major currency pairs.
A dollar crash is not the base case. The dollar still benefits from deep capital markets, reserve-currency demand and relatively high US yields. The forecast instead points to a gradual, uneven depreciation against several major currencies as interest-rate differentials narrow.
The dollar is supported by relatively high US interest rates, resilient domestic demand, deep financial markets and its role as the world’s primary reserve and safe-haven currency.
If rates are within a favourable range, converting a portion now and the rest later can help manage risk and avoid missing opportunities.
USD/CAD responds to the difference between Federal Reserve and Bank of Canada policy, relative US and Canadian data, oil prices and risk sentiment. In September, the tariff measures, the Calgary-Shaw by-election and expectations ahead of the Quebec and Alberta votes add headline risk, although rates, data and oil should remain the dominant catalysts.
Use tools like live exchange rates, rate alerts, and forward contracts, and avoid banks that charge hidden FX margins. Planning ahead can help reduce the risk of converting after a sudden market move.
No currency is risk-free. The US dollar remains the primary global safe-haven currency, while the Swiss franc and Japanese yen can also benefit during periods of stress. The appropriate currency for a business is usually the one that matches its underlying revenues, costs and liabilities.
The forecasts suggest gradual rather than abrupt depreciation through 2027 as interest-rate differentials narrow. The dollar should nevertheless retain structural support from global reserve demand.
Currencies reprice continuously as new information changes expectations for interest rates, growth, inflation and risk. Around high-impact releases, automated trading and thinner liquidity can amplify the initial move, even when the underlying data change only slightly.
Use FX providers that offer competitive rates, compare pricing in real time, and avoid hidden fees typically charged by traditional banks.
With MTFX, you can send money to over 190 countries in 50+ currencies—quickly, securely and at competitive rates.


We make sending money simple
Personal transfers
Sending money abroad? We’ve got you covered with low fees, great rates and no hassle.
Business transfers
Global payments made easy, with fast transfers, great exchange rates and personalized service.
Ecommerce transfers
Get paid, no matter where your customers are. Simple, secure payments for your online store.
Personal transfers
Sending money abroad? We’ve got you covered with low fees, great rates and no hassle.
Business transfers
Global payments made easy, with fast transfers, great exchange rates and personalized service.
Ecommerce transfers
Get paid, no matter where your customers are. Simple, secure payments for your online store.
How to send money with MTFX
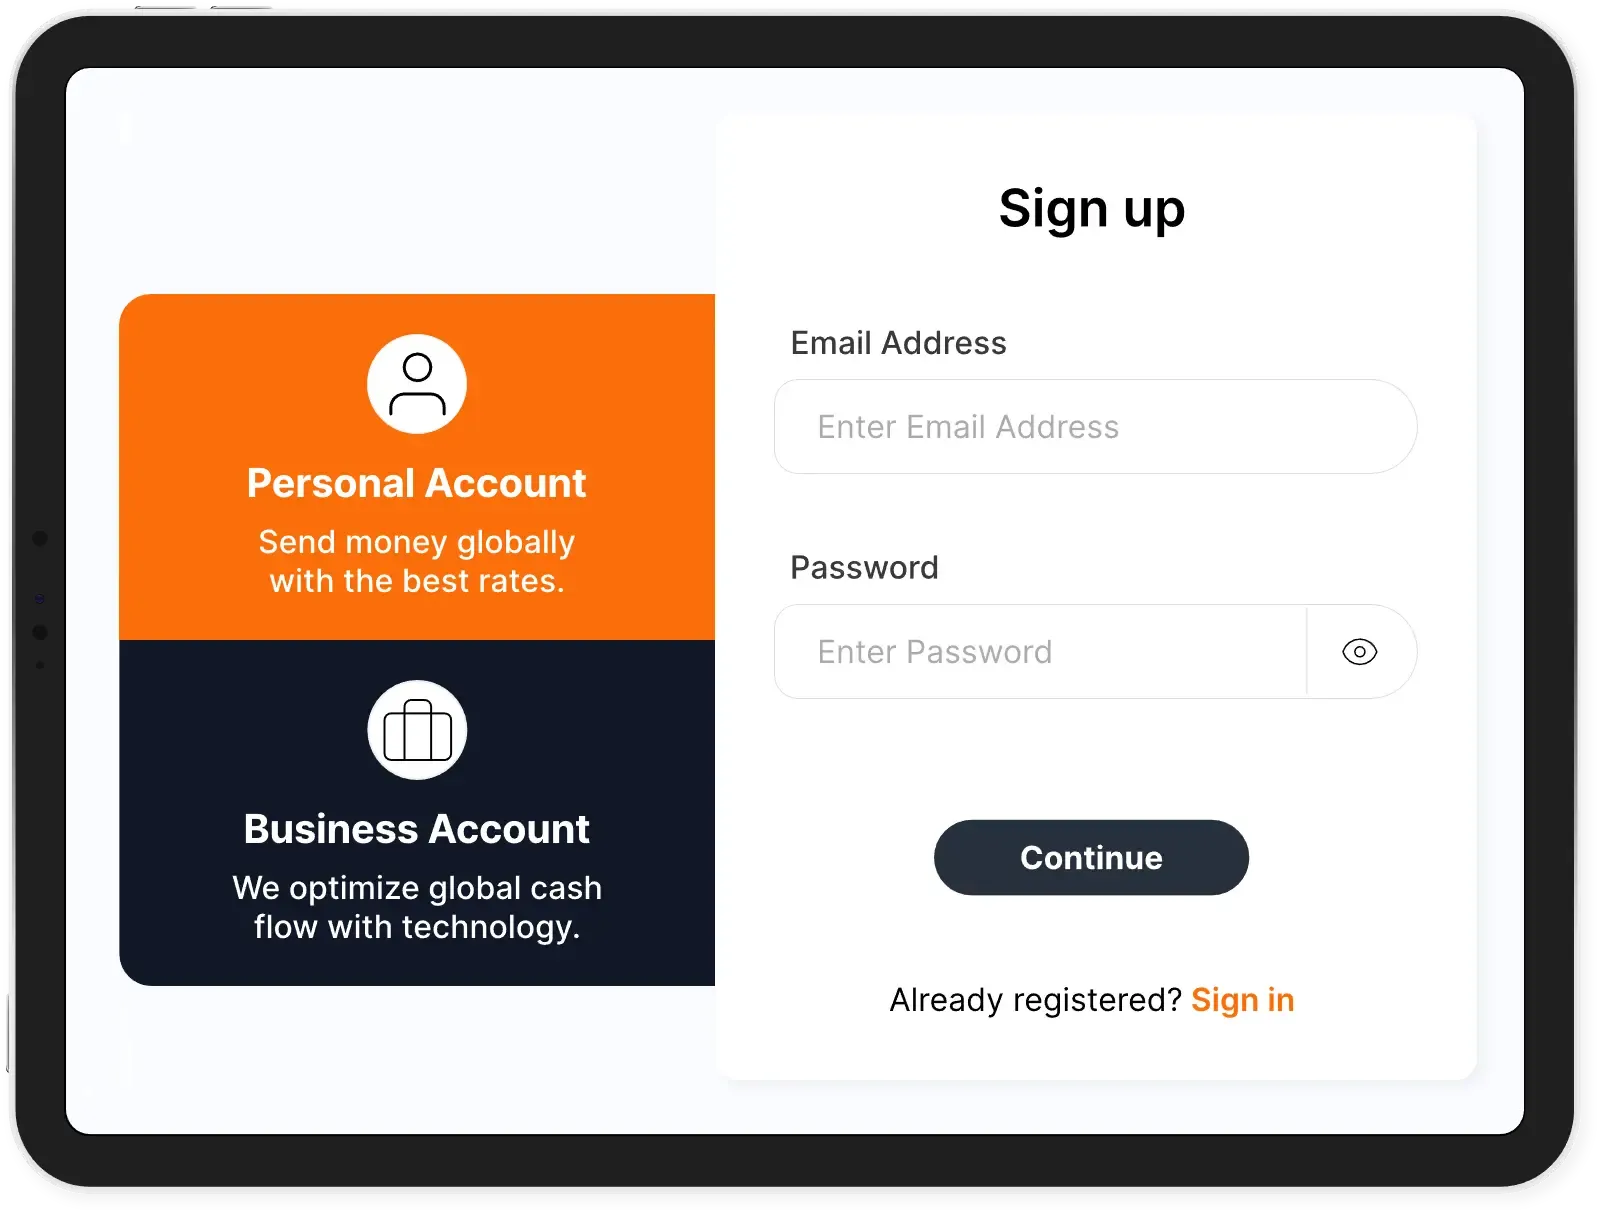
Open your personal or business account and start saving on international money transfers.
- 1Sign up for free
Create your account in less than five minutes—no setup fees or hidden charges.
- 2Get a real-time exchange rate
Instantly access competitive exchange rates for your transfer amount and destination.
- 3Enter recipient information
Provide your recipient’s banking details to ensure fast and secure delivery of funds.
- 4Confirm and send your transfer
Review the details, complete your transaction, and track your transfer every step of the way.
What drives monthly changes in the US dollar exchange rate?
The USD dollar exchange rates shift monthly based on economic data, monetary policy, and global events. While some changes are minor, others can significantly impact international payments and investments.
Key factors behind monthly USD moves:

Federal Reserve policy
Rate hikes or dovish signals can strengthen or weaken the dollar.

Inflation reports
Data like CPI and PPI shape expectations for interest rate changes.

Employment figures
Nonfarm payrolls and jobless rates reflect overall economic health.

GDP growth
Strong or weak economic performance affects USD sentiment.
How much can the US dollar move in a month?
The US foreign exchange rates can fluctuate by 1% to 3% against major currencies in a typical month. However, during periods of high volatility—such as interest rate hikes or geopolitical shocks—monthly movements may exceed 5%, especially against currencies like the Japanese yen or emerging market pairs.
These shifts directly impact the cost of international transactions, from sending money abroad to paying overseas suppliers. Staying informed on the USD forecast and understanding what drives these changes helps individuals and businesses make smarter financial decisions and manage currency risk more effectively.