The Hidden Costs of Cross-Border Payments for Canadian Businesses
Cross-border payment costs can include transfer fees, exchange-rate markups, intermediary-bank deductions, receiving-bank charges, payment-routing costs, and expenses caused by delays or failed transactions. Businesses should compare the total amount debited with the amount the recipient receives, not only the advertised transfer fee to understand the true cost.
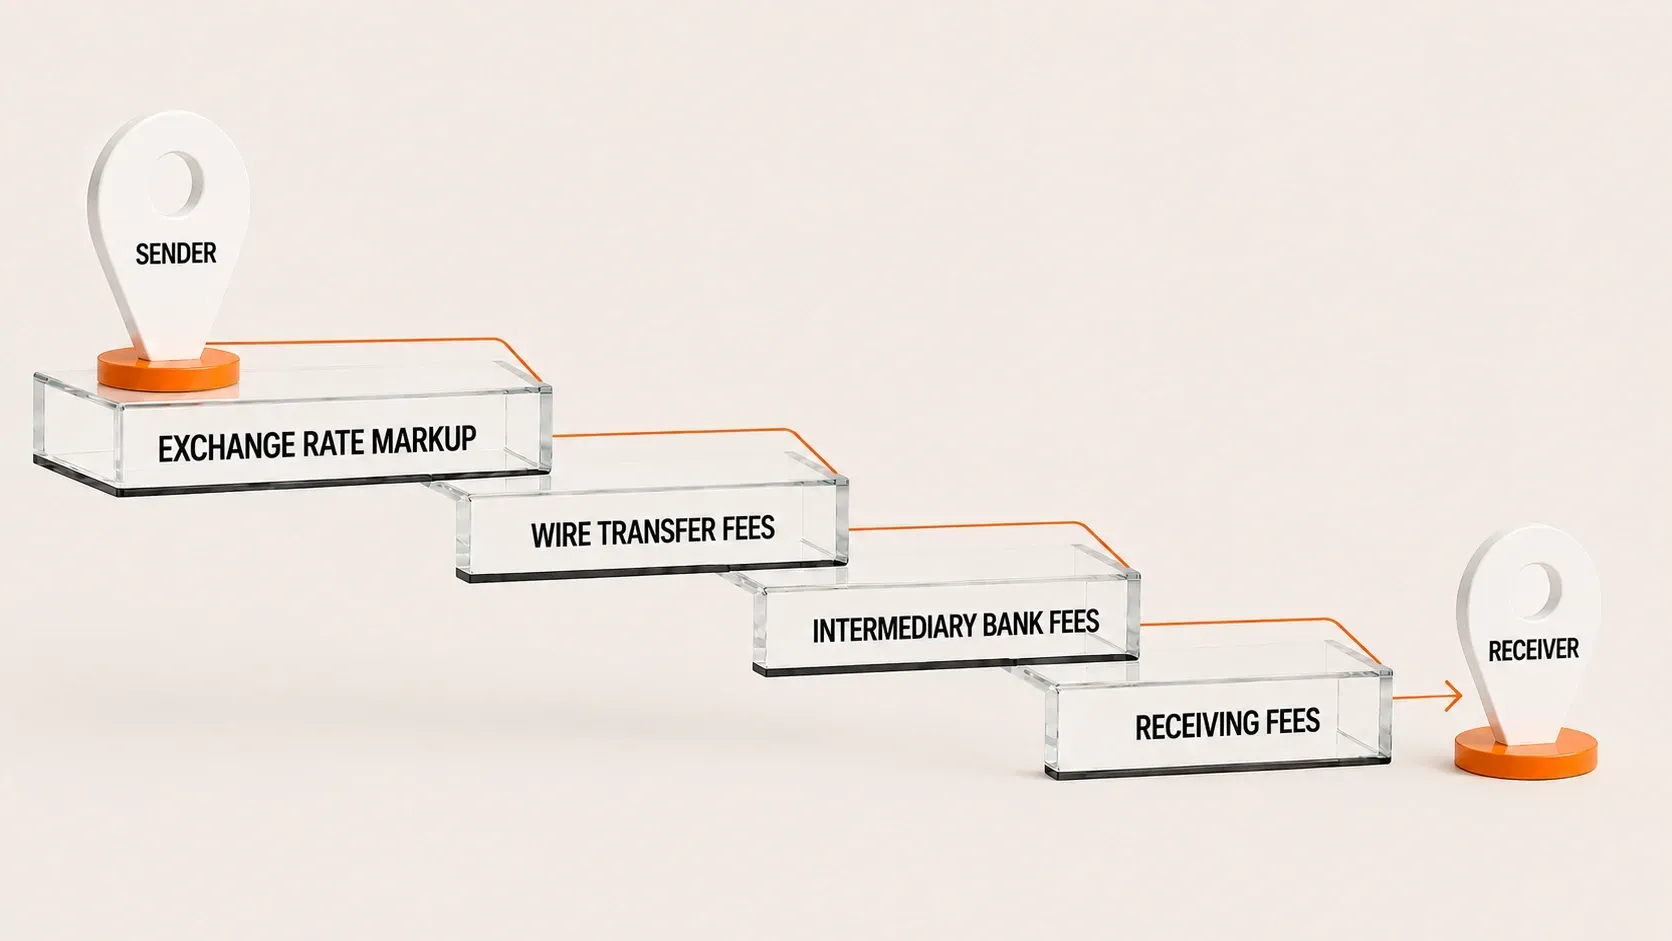
Cross-border payments can cost more than the fee shown on a bank statement. The real expense may include an exchange-rate markup, wire fee, intermediary-bank deduction, receiving-bank charge, payment repair fee, and the financial impact of delays. A transfer advertised as low-cost can therefore deliver less value than expected.
For Canadian businesses paying overseas suppliers, contractors, employees, or international partners, these costs can gradually reduce profit margins. The impact becomes more significant when payments are large, frequent, made in several currencies, or processed through inefficient payment routes.
MTFX has supported businesses with foreign exchange and global payments since 1996. As a Canadian-based, FINTRAC-registered money services business, MTFX provides international business payments, competitive exchange rates, multi-currency capabilities, payment tracking, and specialist FX support.
What are the hidden costs of cross-border payments?
The hidden costs of cross-border payments include expenses that are not always visible in the advertised transfer fee. They may include an FX markup built into the exchange rate, intermediary and receiving-bank deductions, payment-routing charges, failed-payment fees, and costs caused by settlement delays or manual processing.
The best way to compare providers is to review the amount leaving your business, the amount reaching the recipient, and the time and work required to complete the payment.
What is a cross-border payment?
A cross-border payment is a transaction in which the payer and recipient are located in different countries. The payment may also involve converting one currency into another through a bank, a specialist foreign exchange provider, or another international payment platform.
Businesses commonly use international business money transfers for:
- Paying foreign suppliers and manufacturers
- Paying international contractors or employees
- Moving funds between overseas subsidiaries
- Purchasing inventory, equipment, or professional services
- Paying software subscriptions and licensing fees
- Refunding international customers
- Settling freight, logistics, or customs-related invoices
- Sending royalties, commissions, or marketplace payouts
Not every international payment follows the same route. Some transfers are processed through the SWIFT network, while others use domestic or regional payment rails in the recipient's country. The payment method, destination, currency, value, and urgency can all affect the final cost.
What makes up the true cost of an international payment?
The true cost of an international payment is rarely represented by one number. Several charges and operational factors can influence how much the business pays and how much the recipient ultimately receives.
1. Transfer and processing fees
A provider may charge a flat transfer fee, a percentage of the transaction, or a combination of both. Businesses may also encounter wire initiation fees, urgent-payment charges, account fees, amendment fees, or charges for cancelling a transfer.
A flat fee may appear insignificant on a large transaction but become expensive when a business sends many smaller payments. Percentage-based pricing can have the opposite effect, becoming more costly as the transaction value rises.
The word “free” should not be treated as proof that a transaction has no cost. A provider may waive the visible transfer fee while earning revenue through the exchange rate.
2. Exchange-rate markups
The exchange rate is often one of the largest costs in a transaction involving currency conversion. A bank or payment provider normally starts with a market reference rate and applies a margin before quoting the customer.
The difference may appear small when viewed as a decimal, but it can materially affect a large supplier invoice. Businesses can monitor general currency movements through the live exchange rates page before requesting a transactional quote.
For example, one provider may charge a visible transfer fee but offer a stronger exchange rate. Another may advertise a zero-dollar fee but apply a wider FX markup. The second provider may look cheaper while requiring more Canadian dollars to complete the same foreign-currency payment.
The Bank of Canada exchange-rate data may be used as a general market reference, although published reference rates are not necessarily the rates available for a commercial transaction.
3. Intermediary or correspondent-bank fees
Some international wire payments pass through one or more intermediary banks before reaching the recipient. These institutions help route payments between banks that do not have a direct relationship.
An intermediary bank may deduct a handling charge while the payment is in transit. As a result, the sender may not know the final deduction in advance, and the supplier may receive less than the invoice amount.
This can also create reconciliation problems. The buyer may record the invoice as fully paid, while the supplier records a short payment and continues to show an outstanding balance.
4. Beneficiary or receiving-bank fees
The recipient's bank may charge a fee for accepting an international transfer. This charge is separate from the amount paid to the sending bank or payment provider.
A receiving bank may also convert the payment if the currency sent does not match the currency supported by the beneficiary account. For example, sending US dollars to an account that only accepts euros may cause the receiving bank to perform an additional conversion at its own exchange rate.
5. Payment-rail and currency-routing costs
The same payment can have a different cost depending on how it is routed. A traditional international wire may involve several institutions, while a supported local payment route may allow the provider to deliver funds through the recipient country's domestic banking system.
The appropriate route depends on:
- The sending and receiving countries
- The payment currency
- The beneficiary's bank account
- The transaction value
- The required delivery time
- The provider's banking network
- The purpose of the payment
Using an international wire by default may be unnecessary when a reliable local route is available. However, local payment rails may not support every currency, payment value, or transaction type.
6. Amendment, return, and failed-payment fees
International payments can be delayed, amended, or returned when the beneficiary information is incomplete or incorrect. Common causes include:
- An incorrect account or IBAN number
- The wrong SWIFT or BIC code
- A beneficiary name mismatch
- A missing bank address
- An incorrect invoice reference
- An unsupported payment purpose
- A closed or restricted account
- Missing compliance documentation
A failed transfer may result in an amendment fee, recall charge, return fee, or a second currency conversion. Businesses can reduce preventable errors by validating an IBAN number and checking the recipient bank's BIC or SWIFT code before sending funds.
7. Internal administrative costs
The price charged by a financial institution is only one part of the cost. Manual international payment processes also require employees to enter beneficiary details, obtain approvals, contact suppliers, trace delayed payments, and match transfers with invoices.
One payment may take only a few minutes to prepare. Across dozens or hundreds of monthly transactions, however, the labour cost becomes substantial.
Businesses processing regular payment volumes may benefit from payment automation that reduces repeated data entry, inconsistent approval workflows, and reconciliation errors.
Costs caused by payment delays
A delayed international payment may not produce a separate line-item fee, but it can still create a significant business cost.
Possible consequences include:
- Late-payment penalties
- Missed early-payment discounts
- Delayed inventory release
- Suspended supplier credit
- Production interruptions
- Emergency replacement orders
- Damaged vendor relationships
- Additional time spent tracing funds
For companies relying on overseas inventory or time-sensitive shipments, the indirect cost of a delayed payment can exceed the original transfer fee.
How do you calculate the total cost of a cross-border payment?
A useful way to calculate the complete expense is:
Total cross-border payment cost = visible fees + FX markup + intermediary fees + recipient fees + operational costs + delay-related costs
To compare two providers accurately, review the following:
- The total amount debited from the business account
- The exchange rate applied to the transaction
- All transfer, wire, and processing fees
- The amount expected to reach the beneficiary
- The time and internal work required to complete the payment
Companies making USD payments can also review the CAD to USD exchange-rate comparison before arranging a transfer.
| Field | Value |
|---|---|
Amount Payable (USD) 30,000 | |
Bank Exchange Rate 1.4456 / 0.6918 | |
Total cost 43,366.63CAD |
| Field | Value |
|---|---|
Amount Payable (USD) 30,000 | |
MTFX Exchange Rate 1.4208 / 0.7039 | |
Total cost 42,622.59CAD |
You Save
CAD 744.04
with MTFX
16 October 2026
We use mid-market rates. This is for informational purposes only. Log in to view send rates.
Who pays international wire-transfer fees?
International wire charges may be assigned to the sender, shared between the parties, or deducted from the beneficiary's payment. These instructions are commonly described as OUR, SHA, and BEN.
1. OUR fee instruction
Under an OUR instruction, the sender agrees to pay the stated transfer charges. This option is often used when the recipient must receive the full invoice amount.
Businesses should still confirm how charges from other institutions involved in the payment route will be treated.
2. SHA fee instruction
Under a SHA instruction, the sender pays charges imposed by the sending institution, while the recipient pays charges applied by intermediary or receiving banks.
The supplier may therefore receive less than the original payment amount.
3. BEN fee instruction
Under a BEN instruction, relevant payment charges are deducted from the amount sent to the beneficiary. This arrangement should only be used when both parties understand and accept that the recipient will receive less.
The exact treatment can vary by bank, payment route, currency, and account agreement. Finance teams should confirm the instructions before sending a large or time-sensitive payment.
How payment methods affect cross-border payment costs
No single payment method is the cheapest or fastest for every transaction. Businesses should select a payment route according to the destination, currency, value, recipient requirements, and urgency.
1. International bank wires
Bank wires remain widely used because they can reach many countries and institutions. Their cost may include sending fees, intermediary deductions, beneficiary charges, and an FX markup.
They can be suitable for certain high-value or less common payment corridors, but businesses should understand how international wires work and request the complete cost before proceeding.
2. Local payment rails
A provider with access to domestic payment networks may be able to deliver funds locally in the recipient's country. This can reduce the number of financial institutions involved and may improve cost predictability.
Availability depends on the destination, currency, payment value, and beneficiary account.
3. ACH and SWIFT payments
ACH payments generally move through a domestic network, while SWIFT is a global financial messaging system used to facilitate international payment instructions. Each method has different availability, processing times, and cost structures.
Businesses sending funds to the United States can compare the differences between ACH transfers and SWIFT payments before choosing a payment method.
4. Multi-currency accounts
A multi-currency account can be useful when a business regularly receives and pays in the same foreign currency.
For example, a Canadian company receiving USD from customers and paying USD suppliers may be able to use those funds without converting every incoming payment to CAD and then converting back to USD.
This does not remove every payment cost, but it may reduce unnecessary currency conversions.
5. Bulk-payment platforms
Bulk payments allow a company to submit multiple supplier, contractor, or payroll payments through one workflow.
The main benefit may come from operational efficiency rather than a lower fee on each transaction. Finance teams can reduce repeated data entry, apply consistent approval rules, and improve reconciliation.
Which cross-border payment costs have the greatest impact on businesses?
Hidden payment costs become more significant when a company:
- Sends large supplier payments
- Makes frequent recurring transfers
- Operates with narrow profit margins
- Buys in a volatile foreign currency
- Pays recipients in several countries
- Uses manual accounts payable processes
- Receives income in one currency but pays expenses in another
- Depends on time-sensitive international shipments
A small difference in an exchange rate may have little effect on a CAD 500 payment. The same difference can materially affect a CAD 100,000 supplier invoice.
How can businesses reduce cross-border payment costs?
Reducing international payment costs requires more than selecting the provider with the lowest advertised fee. Businesses need to improve how payments are quoted, approved, routed, and reconciled.
1. Compare the total delivered amount
Ask each provider for the total amount that will leave your account and the expected amount the beneficiary will receive. This reveals differences hidden inside the exchange rate or payment route.
2. Review the exchange-rate markup
Compare the quoted customer rate with a recognized market reference. The purpose is not to expect the market rate itself, but to understand the margin included in the transaction.
Businesses can also use currency charts to review recent market movements before deciding when to convert funds.
3. Confirm who will pay bank charges
Agree with the supplier on the appropriate fee instruction before sending funds. For exact-value invoices, determine whether the payment method can deliver the required amount without deductions.
4. Use the correct payment rail
Ask whether the payment can be delivered through a local network rather than a traditional international wire. Consider transaction limits, cost, tracking, and settlement reliability rather than speed alone.
5. Pay suppliers in the agreed invoice currency
Sending the wrong currency can cause an additional conversion at the receiving bank. Confirm the invoice currency and the currency supported by the supplier's account before initiating the payment.
Businesses can review the advantages and disadvantages of different settlement currencies in the guide to paying vendors in foreign currency versus US dollars.
6. Consolidate appropriate recurring payments
Where contract terms permit, combining several small obligations into a larger scheduled payment may reduce repeated transaction fees and administrative work.
However, businesses should not delay urgent invoices simply to create a larger batch. Consolidation should support the payment schedule rather than disrupt it.
7. Validate beneficiary information
Check the supplier's:
- Legal account name
- Account or IBAN number
- SWIFT or BIC code
- Bank name and address
- Payment currency
- Invoice reference
- Payment purpose
Changes to supplier bank details should be confirmed through a trusted communication channel. Email-only requests to replace payment instructions should be independently verified.
8. Use rate alerts and planned conversions
A business cannot predict every market movement, but it can avoid making every currency decision at the last minute.
Currency rate alerts, payment calendars, and pre-agreed decision levels can help finance teams respond more consistently when target rates become available.
9. Consider a multi-currency account
Holding foreign-currency balances may reduce repeated conversions when a business receives and pays in the same currency.
The decision should consider account costs, working-capital requirements, future expenses, and the company's overall foreign exchange risk-management strategy.
10. Automate approvals and reconciliation
A structured workflow can reduce duplicate payments, manual errors, and the time spent matching transfers with invoices.
Automation is particularly useful for companies managing recurring supplier payments, contractor transfers, payroll, or intercompany transactions. Businesses can learn more in the guide explaining what payment automation is and why it matters.
Save on international transfers with competitive FX rates from MTFX.
Should businesses pay suppliers in CAD, USD, or local currency?
The best payment currency depends on the supplier agreement and which party is best positioned to manage the currency conversion.
- Paying in Canadian dollars
Paying in CAD transfers the currency-conversion responsibility to the supplier. The supplier may build an additional buffer into its price to protect against an uncertain exchange rate.
The Canadian business may not know how much of the invoice reflects that currency buffer.
- Paying in US dollars
USD is widely used in international trade, but it is not automatically the most efficient option. A European or Asian supplier may need to convert USD into its domestic currency, creating another conversion cost.
- Paying in the supplier's local currency
Paying in local currency may give the Canadian buyer greater control over the exchange rate. It may also allow the supplier to quote a cleaner price because it no longer needs to manage the FX conversion.
The decision should be based on the total cost rather than an assumption that one currency is always cheaper. The guide to paying foreign suppliers in their own currency explains this decision in more detail.
Cross-border payment mistakes that increase costs
Many unnecessary costs come from process gaps rather than unavoidable banking charges. A clear international payment policy can prevent common problems before money is sent.
- Comparing providers by transfer fee alone
- Accepting an exchange rate without reviewing the markup
- Sending a currency the beneficiary account cannot accept
- Ignoring possible intermediary-bank deductions
- Using incomplete or outdated supplier details
- Sending many small wires without reviewing batching options
- Initiating payments too close to the invoice deadline
- Allowing avoidable currency conversion at the receiving bank
- Failing to confirm OUR, SHA, or BEN instructions
- Using the same payment route for every country
- Paying updated bank details without independent verification
- Failing to reconcile the amount credited to the supplier
- Treating delayed-payment administration as a free task
Finance teams can also review these common international payment mistakes before building a formal payment checklist.
What should you compare when choosing a cross-border payment provider?
A suitable provider should make it easier to understand the complete cost and payment process rather than focusing only on a headline fee.
The right provider should match the company's transaction patterns. A business sending one payment each year has different requirements from an accounts payable team managing hundreds of international invoices.
The guide on choosing an international payment provider offers additional considerations for Canadian companies.
How MTFX helps Canadian businesses control international payment costs
MTFX helps Canadian businesses manage international payments through an online platform supported by currency specialists. Companies can use MTFX to pay international invoices, transfer funds to suppliers, manage multi-currency transactions, and support recurring global payment requirements.
- Access competitive exchange rates for international business payments
- Pay overseas suppliers in supported foreign currencies
- Manage and track payments through an online platform
- Use rate alerts and FX risk-management solutions
- Receive specialist support for recurring or higher-value transfers


Take control of the full cost of every international payment with MTFX
The cheapest-looking cross-border payment is not always the least expensive. A low or zero transfer fee can be offset by a wider exchange-rate markup, intermediary deductions, receiving-bank charges, or a payment process that consumes hours of staff time.
Before sending funds, compare the complete amount debited, the exchange rate, the expected delivered amount, the payment route, and the settlement time. A consistent review process can help protect margins, reduce reconciliation problems, and improve relationships with overseas suppliers.
Businesses that regularly pay international suppliers, contractors, employees, or partners can use MTFX to manage global payments, compare exchange rates, and access specialist FX support. Sign up with MTFX to gain clearer control over currency conversion and international payment costs.
FAQs
1. What are the hidden costs of cross-border payments?
Hidden costs can include exchange-rate markups, intermediary-bank fees, receiving-bank charges, payment-rail costs, failed-payment fees, and expenses caused by delays or manual processing.
2. Why are cross-border payments expensive?
Cross-border payments may involve currency conversion, multiple financial institutions, compliance checks, international banking networks, and receiving-bank charges. Each part of the process can add cost.
3. What is an exchange-rate markup?
An exchange-rate markup is the margin added by a bank or provider to a market reference rate. It is included in the customer's exchange rate rather than shown as a separate transfer fee.
4. Do intermediary banks charge international payment fees?
They can. When a payment passes through a correspondent or intermediary bank, that institution may deduct a processing fee before forwarding the funds.
5. Why did my supplier receive less than I sent?
The difference may result from intermediary fees, receiving-bank charges, shared fee instructions, or currency conversion performed by the supplier's bank.
6. What do OUR, SHA, and BEN mean?
OUR means the sender agrees to pay the stated charges. SHA means charges are shared between the sender and recipient. BEN means fees are deducted from the beneficiary's payment.
7. How can businesses reduce international payment fees?
Businesses can compare the all-in cost, review the FX markup, select the correct payment route, validate beneficiary details, consolidate suitable payments, and avoid unnecessary currency conversions.
8. Is it cheaper to pay a supplier in local currency?
It can be. A local-currency payment may remove the supplier's need to add an FX buffer, but the buyer should compare the exchange rate, transfer fee, and delivered amount before deciding.
9. Are international payment fees tax deductible in Canada?
Some business-related financial charges may qualify as deductible expenses, depending on the circumstances. Businesses should retain complete records and confirm the treatment with a qualified tax professional or current CRA guidance.
10. How long do cross-border business payments take?
Delivery time depends on the destination, currency, payment rail, cut-off time, compliance review, beneficiary bank, and whether intermediary institutions are involved.